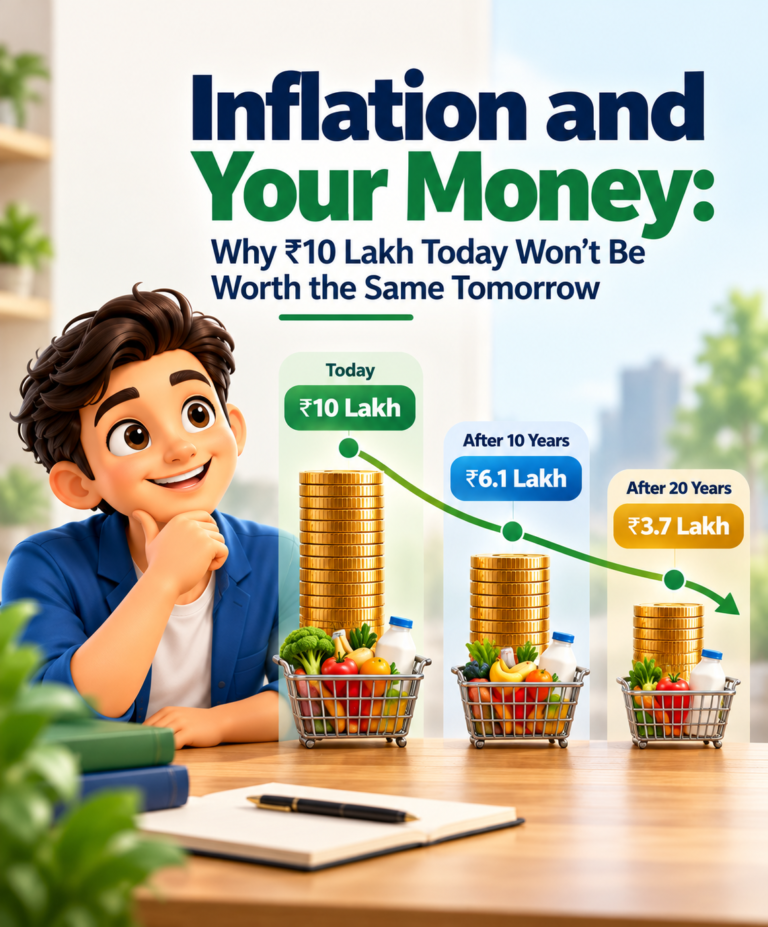
Imagine you have ₹10 lakh today.
It sounds like a substantial amount of money. But will ₹10 lakh have the same purchasing power 10 or 20 years from now?
Probably not.
The reason is inflation.
Inflation means that the prices of goods and services increase over time, which means the same amount of money may buy fewer things in the future.
This is one of the most important concepts to understand when planning for long-term financial goals.
Whether you are saving for your child’s education, buying a home, planning for retirement or building long-term wealth, ignoring inflation can result in significantly underestimating how much money you will actually need.
What Is Inflation?
Inflation is the gradual increase in the general prices of goods and services over time.
When prices rise, the purchasing power of money falls.
For example, suppose a basket of everyday goods costs ₹5,000 today.
If the prices of those goods increase over the years, the same basket may cost considerably more in the future.
Your ₹5,000 has not disappeared. However, its purchasing power has reduced.
This is why simply keeping track of the amount of money you have is not enough. You also need to consider what that money will be able to buy in the future.
Why ₹10 Lakh Today May Not Be Enough Tomorrow
Suppose you have ₹10 lakh today and you are planning to use it for a financial goal several years from now.
If the cost of the goods or services associated with that goal increases over time, you may need more than ₹10 lakh when the time comes.
For example, imagine that a particular financial goal costs ₹10 lakh today.
If the cost of achieving that goal increases every year because of inflation, the future amount required could be significantly higher.
This is why financial planning should focus on the future cost of a goal, not just its current cost.
How Does Inflation Affect Your Financial Goals?
Inflation can affect almost every major financial goal.
1. Children’s Education
Education costs can increase over time.
If higher education costs ₹15 lakh today, you should not automatically assume that ₹15 lakh will be sufficient when your child starts college several years from now.
A long-term education plan should consider the potential increase in education costs.
2. Buying a Home
Property prices and related expenses can change over time.
If you are planning to purchase a home several years from now, the amount you need for the down payment and other expenses may be different from what you would need today.
3. Retirement
Inflation becomes especially important during retirement because you may need to fund your expenses for many years without regular employment income.
A monthly household expense of ₹50,000 today could be substantially higher in the future.
Therefore, retirement planning should account for the rising cost of living.
4. Healthcare
Healthcare is another area where future expenses can be difficult to predict.
Medical treatment, medicines, consultations and other healthcare-related expenses can increase over time.
This makes adequate financial preparation particularly important.
Understanding the Difference Between Today's Value and Future Value
One of the simplest ways to understand inflation is to compare the purchasing power of money across different periods.
Suppose you need ₹10 lakh today for a particular goal.
If inflation averages 6% per year, the future amount required after 10 years would be approximately:
₹10 lakh × (1.06)¹⁰ ≈ ₹17.91 lakh
In other words, if the cost of your goal rises at an average rate of 6% annually, you may need around ₹17.91 lakh after 10 years to have purchasing power equivalent to ₹10 lakh today.
This is an illustration, not a prediction of future inflation.
The actual inflation rate can be higher or lower.
The Longer the Time Horizon, the More Inflation Matters
Inflation compounds over time.
This means that even a seemingly moderate inflation rate can have a significant impact over several decades.
Consider a simplified illustration:
Time Period | Future Amount Needed for ₹10 Lakh Today at 6% Inflation |
Today | ₹10.00 lakh |
5 years | ₹13.38 lakh |
10 years | ₹17.91 lakh |
15 years | ₹23.97 lakh |
20 years | ₹32.07 lakh |
25 years | ₹42.92 lakh |
These figures are purely illustrative and assume a constant 6% annual inflation rate.
The important lesson is not the exact number.
The lesson is that time can significantly magnify the effect of inflation.
Inflation Can Quietly Reduce Your Wealth
One of the biggest problems with inflation is that you may not notice its impact immediately.
Suppose your salary increases over time.
At first, you may feel that you are earning significantly more than you did several years ago.
But if your expenses have increased at the same time, your actual improvement in purchasing power may be smaller than it appears.
The same principle applies to your savings.
If your money grows at a rate that is lower than inflation over a long period, its purchasing power may decline.
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Ut elit tellus, luctus nec ullamcorper mattis, pulvinar dapibus leo.
Why Keeping All Your Money in Cash May Not Be Enough
Keeping some money readily available is important for liquidity and emergencies.
However, holding all your long-term savings in cash or low-growth instruments can create another challenge.
If the rate at which your money grows is consistently below inflation, your money may lose purchasing power over time.
This does not mean that every investor should take high investment risk.
Instead, your financial strategy should consider:
Safety + Liquidity + Growth + Inflation
The appropriate balance depends on your goals, time horizon and risk profile.
Inflation and Your Investments
When planning investments, it is useful to think about real returns.
A simple way to understand this is:
Real return ≈ Investment return − Inflation
For example, if an investment earns 8% and inflation is 6%, the approximate real return is 2%.
The actual calculation of real return uses compounding:
Real return = [(1 + investment return) ÷ (1 + inflation)] − 1
This distinction matters because earning a positive return does not necessarily mean that your purchasing power has increased significantly.
Should You Try to Beat Inflation?
For long-term financial goals, investors generally need to consider whether their investment strategy has the potential to grow faster than inflation over the relevant period.
However, “beating inflation” should not mean taking unnecessary risks.
Your investment approach should depend on:
- Financial goal
- Investment horizon
- Risk tolerance
- Income stability
- Liquidity requirements
- Existing investments
- Overall financial situation
A short-term goal may require a different strategy from a goal that is 20 or 30 years away.
Inflation and Goal-Based Investing
This is why inflation is an important part of goal-based investing.
Suppose you want to build ₹20 lakh for your child’s education.
If the goal is 12 years away, simply saying:
“I need ₹20 lakh.”
may not be enough.
Instead, you should consider what the education cost could be in the future.
The same principle applies to:
- Home purchase
- Retirement
- Children’s marriage
- Business plans
- Healthcare
- Other major financial goals
Your target should reflect the estimated future cost, not only today’s price.
How Can You Plan for Inflation?
1. Start Early
The earlier you start investing for a long-term goal, the more time you have to build the required corpus.
2. Increase Investments Over Time
As your income increases, consider whether you can increase your regular investment contributions.
This can help your investment plan keep pace with rising financial requirements.
3. Use Different Asset Classes
Depending on your risk profile and investment horizon, diversification across suitable asset classes may help your portfolio pursue growth while managing risk.
4. Review Your Financial Goals
The amount you originally estimated may no longer be adequate after several years.
Review your goals periodically and adjust your investment strategy when necessary.
5. Don’t Focus Only on the Final Amount
Instead of asking only:
“How much money do I have?”
also ask:
“What will this money be worth in terms of purchasing power when I need it?”
This can lead to more realistic financial planning.
A Simple Example: Planning for Retirement
Suppose your current household expenses are ₹60,000 per month.
You plan to retire 20 years from now.
If inflation averages 6% annually, the equivalent monthly expense after 20 years would be approximately:
₹60,000 × (1.06)²⁰ ≈ ₹1.92 lakh
So, ₹60,000 of monthly expenses today could require roughly ₹1.92 lakh per month in 20 years to maintain equivalent purchasing power under this illustration.
This is why simply multiplying today’s expenses by the number of retirement years can underestimate the amount you may eventually need.
Common Mistakes People Make About Inflation
Mistake 1: Ignoring Inflation While Setting Goals
Using today’s prices for a goal that is many years away can result in an insufficient target.
Mistake 2: Looking Only at Investment Returns
An investment may generate positive returns but still provide limited growth in purchasing-power terms if inflation is high.
Mistake 3: Assuming Salary Increases Automatically Solve the Problem
Higher income does not necessarily mean higher savings if expenses are rising at the same time.
Mistake 4: Planning Retirement Using Today’s Expenses
Retirement may be decades away, making inflation an especially important consideration.
Mistake 5: Taking Excessive Investment Risk
The need to beat inflation does not justify taking risks that are unsuitable for your financial situation.
The Bottom Line
Inflation is one of the biggest factors that can quietly affect your long-term financial plans.
₹10 lakh today and ₹10 lakh 20 years from now are not necessarily equal in purchasing power.
As prices rise, you may need more money in the future to achieve the same financial goal.
That is why effective financial planning should consider:
Today’s cost → Inflation → Future requirement → Investment strategy → Regular review
Whether you are planning for education, a home, retirement or long-term wealth creation, accounting for inflation can help you set more realistic targets.
The goal is not simply to accumulate a large amount of money.
The goal is to build enough wealth to maintain your desired purchasing power and achieve your financial goals in the future.
Disclaimer: This article is for educational and informational purposes only and should not be considered investment, financial or tax advice. Inflation rates, investment returns and future expenses can vary. The examples and calculations in this article are illustrative and should not be treated as forecasts or guarantees. Investors should consider their individual goals, risk profile, investment horizon and financial circumstances before making investment decisions.